
The video game and mobile app markets are worth several hundred billion euros, but traditional banks struggle to finance creative studios: long cycles, deferred revenues (distribution platforms, publishers), atypical collateral. This is the niche in which the Triple Dragon group, active since December 2016, has specialised, before launching its direct platform TD Funding (Triple Dragon Funding) in January 2026.
In this article, I review the business model, the group's history, the founders, the regulatory framework, the return, the TD Bonds, the guarantees (collateral and buyback guarantee), taxation and the risks.
For my part, I have already invested €1,000 on TD Funding. My feedback is detailed further down in the article and I will probably increase my position soon.
TD Funding at a glance
Criterion | TD Funding |
|---|---|
Direct platform launch | January 2026 (lending company active since Dec. 2016) |
Platform headquarters | 🇱🇺 Luxembourg: Triple Dragon Funding SARL (RCS B301533), 62 avenue de la Liberté, L-1930 |
Parent company / lending company | Triple Dragon Limited (🇬🇧 United Kingdom, no. 10521765) |
Sector | Financing for video game and mobile app studios |
Secured loan rates | 13.5% / year |
TD Bonds (group debt) | 14% |
Minimum ticket | €1,000 per loan |
Typical term | 6 to 24 months |
Interest payment | Daily interest; option to have interest automatically reinvested |
Geographic diversification | 🇬🇧 United Kingdom |
Guarantee | Collateral + 90-day buyback |
Investor regulation | No ECSP MiFID II licence |
Bonus | 1% cashback during the first 60 days |
My video: Triple Dragon (TD Funding) review
If you prefer the video format, here is my detailed feedback on Triple Dragon and TD Funding: registration, deposit, returns, guarantees, TD Bonds, regulation and the first figures from my portfolio.
What is Triple Dragon?
Triple Dragon is a credit company in the United Kingdom 🇬🇧 that allows you to invest in financing the video game and mobile app industry.
The borrowers are studios that publish on Steam, Google Play, App Store, Xbox, PlayStation, Nintendo Switch, or that work with third-party publishers.
History of the Triple Dragon group
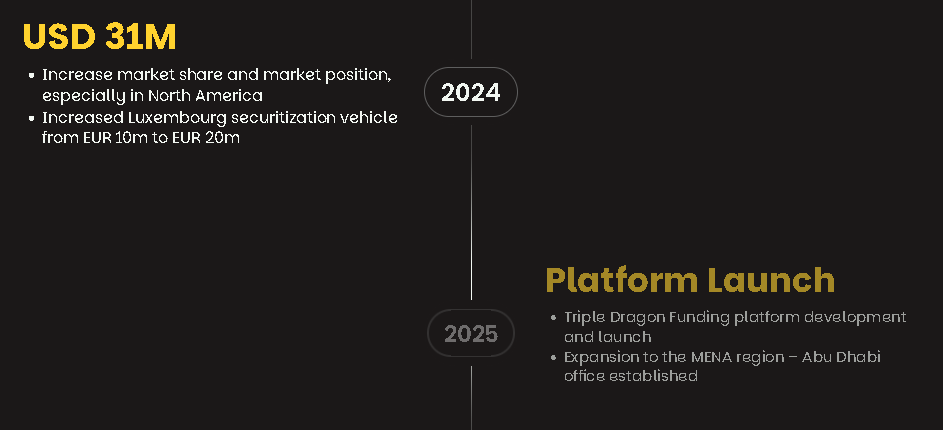
Key dates:
December 2016: creation of Triple Dragon Limited (UK).
2017-2025: portfolio growth through various financings.
January 2026: launch of TD Funding.
August 2026: launch of TD Bonds.
TD Funding: how it works
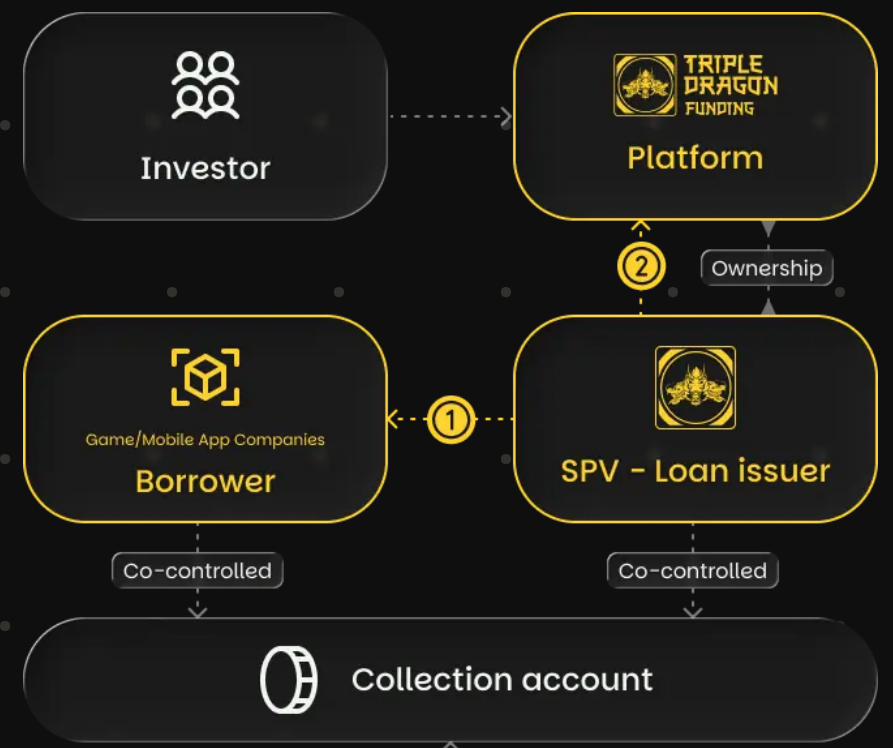
TD Funding (Triple Dragon Funding) is the Luxembourg entity 🇱🇺 that operates the site tdfunding.eu. It does not lend directly to studios: it connects investors with receivables held by group structures (notably TD Funding 2025 Limited, an English lending company).
The diagram above summarises the chain: the investor goes through the TD Funding platform to invest in a group SPV (special purpose vehicle, a dedicated vehicle for financing), which grants the loan to the borrowing studio.
Founders and management team
Shareholders - Triple Dragon Limited (UK)
The group's capital is held by three founding partners:
 Pieter van der Pijl - co-founder, sourcing and structuring gaming deals; background in cross-border mergers and acquisitions. He is often the one who answers the community's sensitive questions.
 Diederik van Lede - business lawyer (London / Brussels), multi-billion M&A experience; non-executive director on several boards of directors.
 Charles Brooke - finance / private equity (real estate, fintech, video games); co-founder in 2017; founder of Warwick Capital.
Operational platform management
 Vitalijs Zalovs - CEO of TD Funding (joined in 2025), former CEO of Esketit. Public contact person on Telegram and investor webinars.
 Jozua Laudams - head of portfolio management (since 2023).
 Ritesh Thadani - head of business development (since 2022).
 Kaloyan Dimitrov - CFO (chief financial officer) since 2019.
Profiles on TD Funding's About page.
Platform statistics (summer 2026)
Orders of magnitude reported on TD Funding's Statistics page:
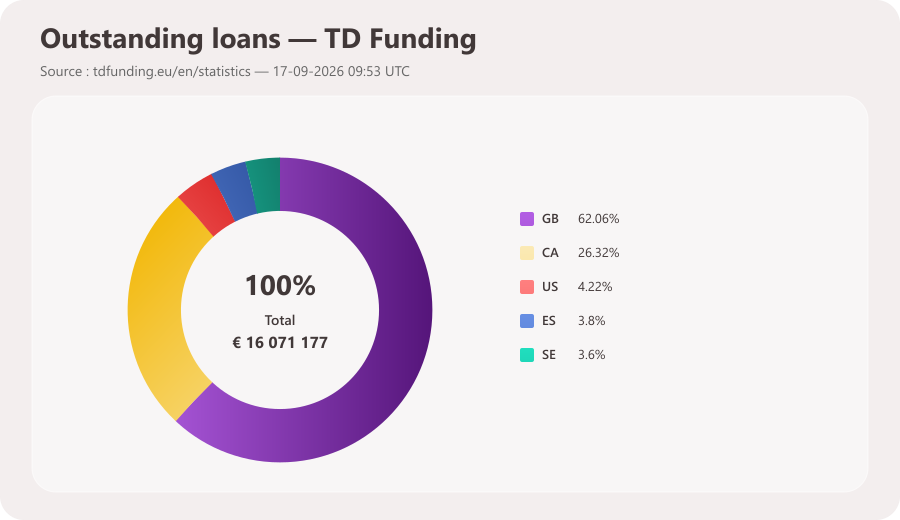
Geographic breakdown of the platform's outstanding portfolio as of 17-09-2026: United Kingdom 62.06%, Canada 26.32%, United States 4.22%, Spain 3.8% and Sweden 3.6%.
Outstanding amount: ~€15M+ (platform), growing rapidly since launch.
Investors: ~1,600+ accounts opened.
Loans with no delay: 100% in the statistics displayed to date (€0 in recovery proceedings at the time of the summer publications).
Interest paid to investors: > €1M cumulative platform total (evolving figure).
Average basket: ~€8,800 per active investor.
Recurring borrowing clients: ~70% of the lending company's portfolio (studio retention).
These figures are provided by the platform: useful for monitoring, not a guarantee. A portfolio with no delay after 9 months does not guarantee the absence of defaults in the years to come.
Financial statements and transparency
Triple Dragon publishes performance reports (monthly / quarterly) in the News section of tdfunding.eu: outstanding amounts, interest paid, early repayments, average net annual return of the platform portfolio.
Examples of figures communicated in 2026:
February 2026 (first full month): outstanding amount ~€6.9M, average APY ~15.21% (compounding effect + new projects at 14%).
Summer 2026: detailed platform figures (outstanding amount, geography, delays) - see the Platform statistics section.
Group (lending activity since 2016): > €50M financed, > €7M in interest paid to investors; a few partial defaults (cumulative written-off receivables < €500k) with investors reimbursed by Triple Dragon according to the group's communications. This track record does not constitute a promise for the future.
On the British parent company side, management documents are circulated. These are management figures, not audited consolidated accounts. For the TD Bonds, the community's recurring criticism is the lack of consolidated balance sheet for the parent company that is as detailed as for project loans: you are lending to the group, not to a studio with identifiable collateral.
I will follow the publications on my P2P Financial Statements page if documents are communicated soon.
Regulation and legal framework
Unlike Lendermarket, Mintos (ECSP) or IUVO (MiFID II), TD Funding is not authorised under ECSP or MiFID II for investors to date. The platform relies on the prospectus exemption (Regulation (EU) 2017/1129, Art. 1(4)(b)): each offer is capped at 149 investors per Member State - hence the Request investment offer step before each investment.
An application for a PSFP licence (crowdfunding service provider) in Luxembourg has been announced since Q2 2026, with an indicative timeframe of around 12 months (timeline still uncertain).
In practice for you: no harmonised FICI and no MiFID cap at €20,000; you buy private receivables / debt securities via a Luxembourg contract - read the general terms of use (version dated 18 December 2025). Regulation of lenders on the borrower side (UK, Canada, US) protects the studios, not your investor portfolio.
My P2P comparison tool (regulation view) and my article on crowdlending regulation place TD Funding in the “without European authorisation directly protecting the investor” category: it is not illegal and other platforms have long operated this way (PeerBerry, etc.), but the procedural risk is a little higher if the platform fails.
How to invest on the platform?
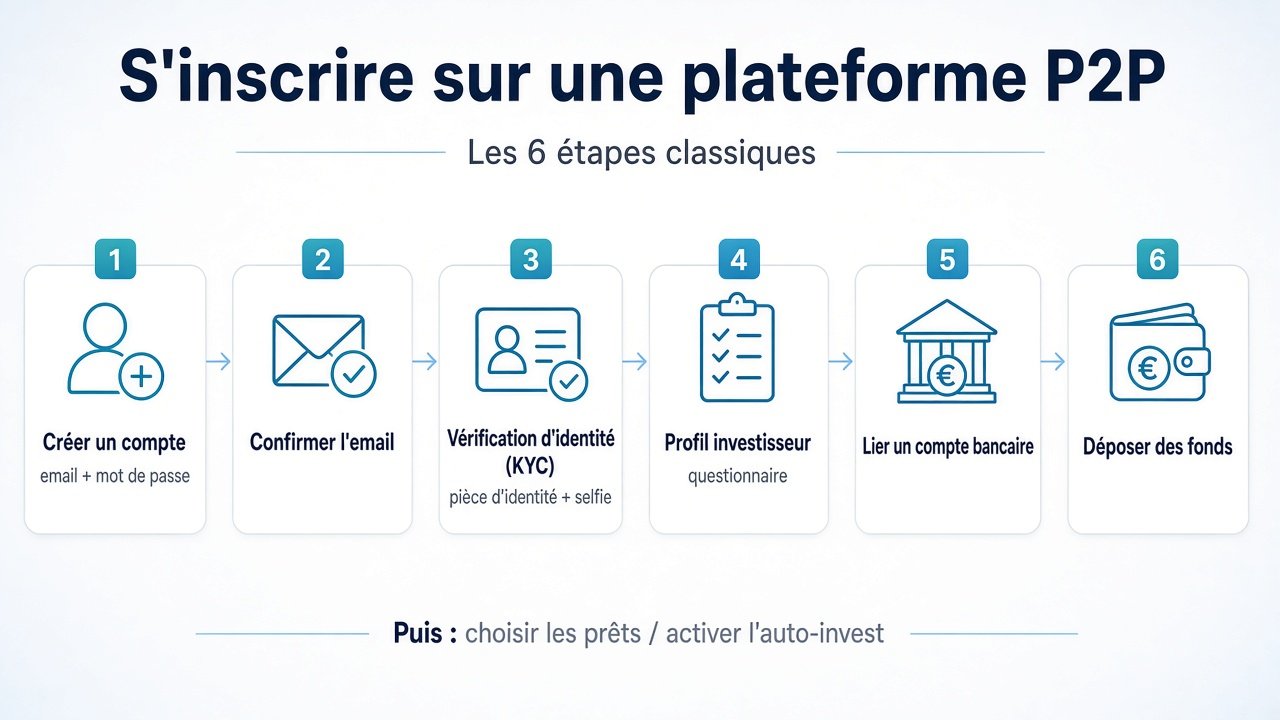
TD Funding is not a fixed-rate savings product: you invest in identified loans, one by one. Here is the typical process:
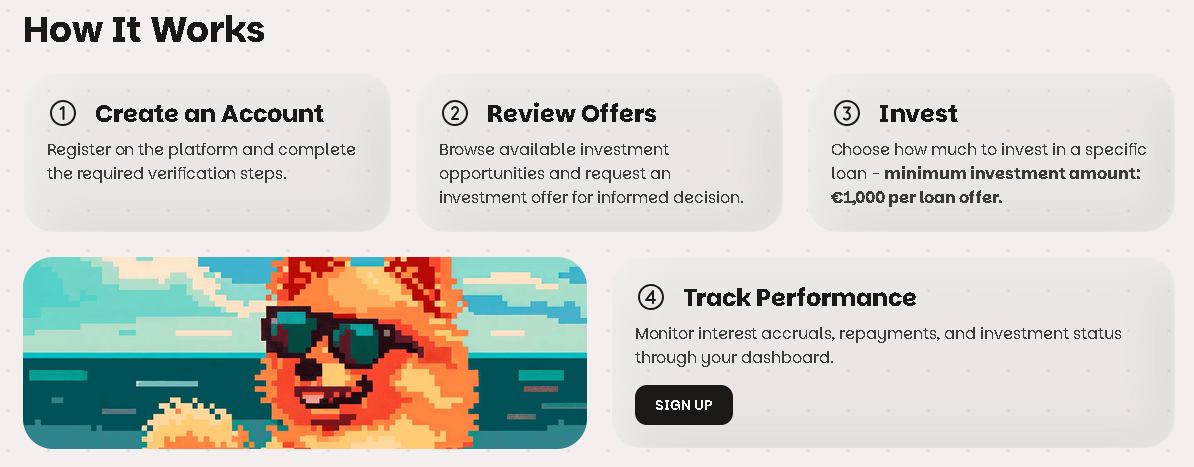
Registration and KYC - EEA residence (including France), minimum age 18, ID document, selfie, sometimes proof of address. Lender questionnaire (income, assets, experience) required for the prospectus exemption.
Legal entities are accepted (enhanced KYC).Deposit - SEPA transfer in EUR to the IBAN displayed in the member area after profile validation (no bank card). In my case, the credit generally appears on the account in less than an hour.
Investment in a loan - analyse the project sheet (borrower, collateral, term, rate, LTV).
€1,000 minimum at around 13-14% (term 6 to 24 months).Interest payment - interest is credited to your investor account (daily payment, compounding possible).
No auto-invest: each project is chosen manually.
Support: info@tdfunding.eu, official Telegram group.
Interface and usability
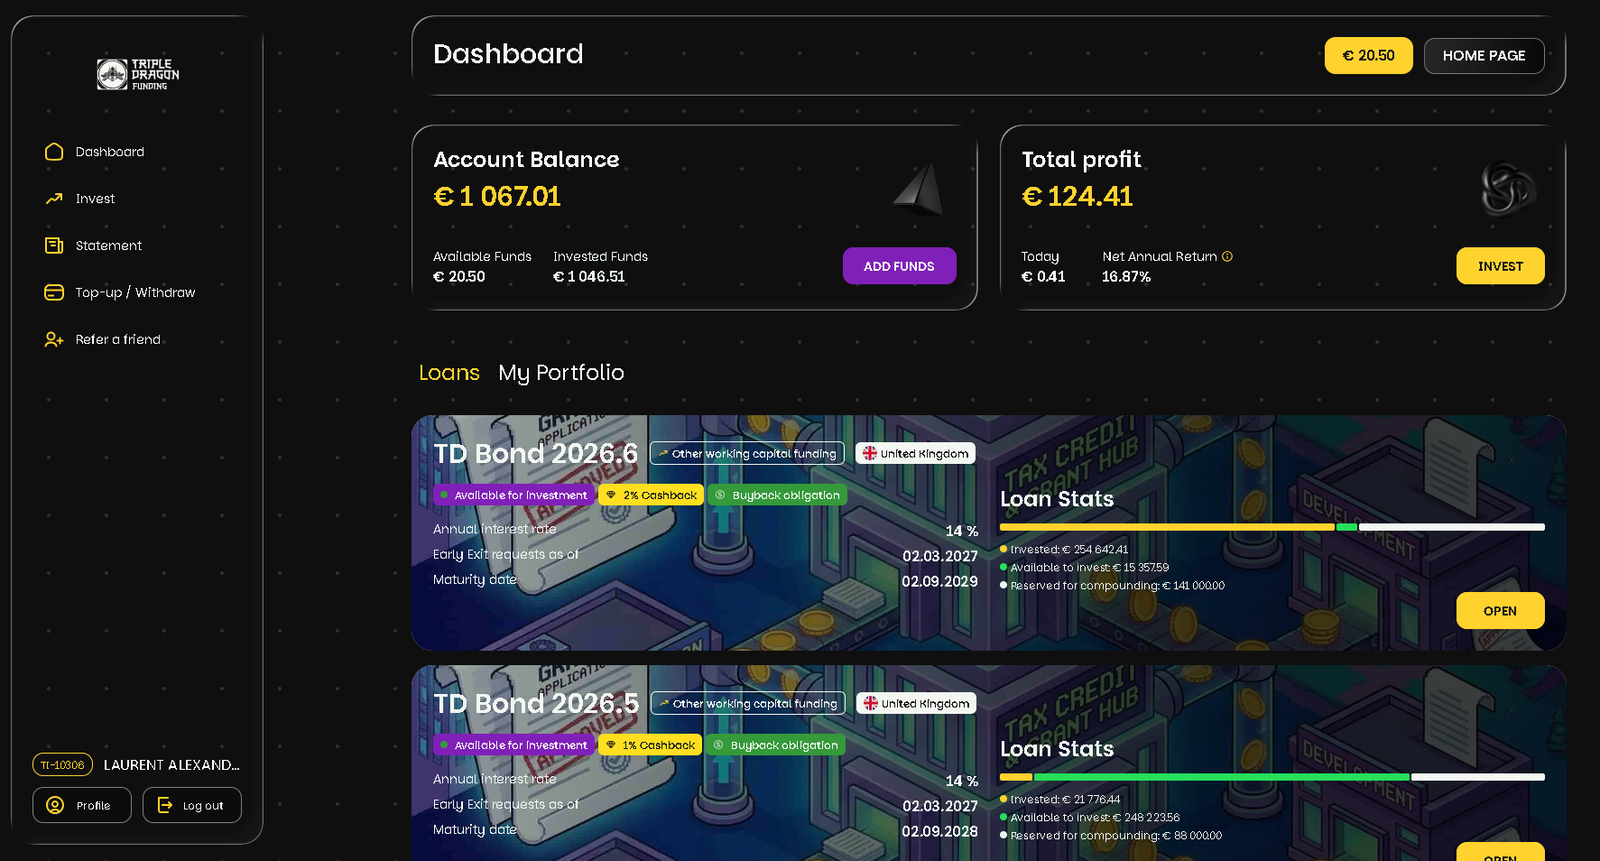
The dark interface is clean and rather pleasant to use.
✅ Positive points:
Detailed project sheets (borrower, collateral, documents).
Portfolio dashboard with interest, compounding, history.
Public Statistics section (outstanding amounts, performance).
Export function available (transactions, etc.).
⚠️ Weak points:
No mobile app.
Interface in English.
Products: secured loans vs TD Bonds
TD Funding offers two families of investments that must be clearly distinguished:
Criterion | Secured loans | TD Bonds |
|---|---|---|
Issuer | Loan to a studio via an SPV, backed by collateral | Loan to Triple Dragon Limited (group) |
Rate (summer 2026) | 13.5% / year | 14% + 1% cashback (2 years) or 2% (3 years) |
Since 14 August 2026, the rate on new secured loans has fallen from 14% to 13.5%, while TD Bonds remain at 14% + cashback according to the current offer.
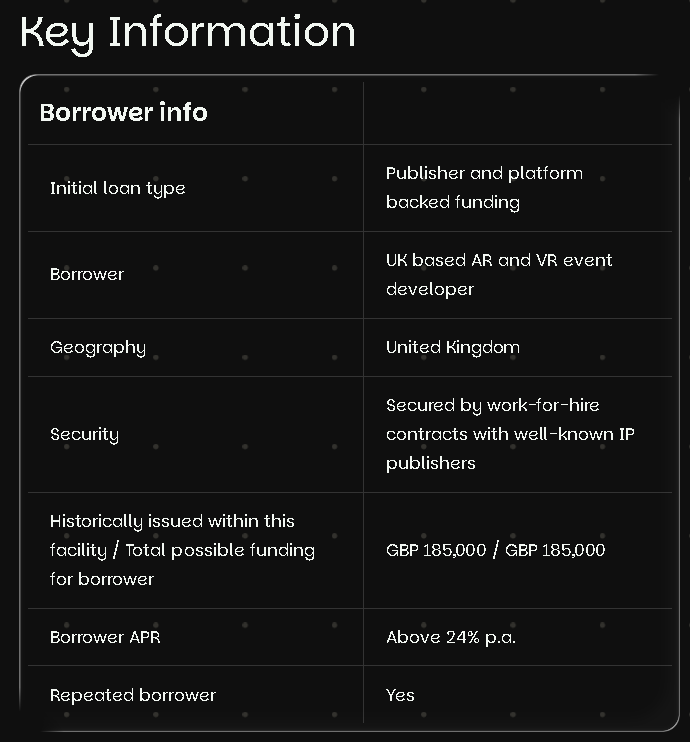
On the project sheet, the studio often displays a Borrower APR above 24% p.a.: the rate paid by the borrower is significantly higher than the one paid to investors, which leaves a margin for the group (fees, provisions, buyback).
Collateral and types of guarantees

Collateral for secured loans
Each opportunity is a secured senior loan backed by identifiable collateral (platform receivables, publishers, public aid). The group requires coverage of at least 120% of the outstanding amount.
Cash flows (Apple, Google, Steam, publishers, tax credits, etc.) are assigned as a priority to loan repayment, via collection accounts or control of receivables. This is not a state guarantee: it is the contractual framework of senior financing.
Indicative portfolio breakdown (early 2026):
39%: tax credits and grants (R&D, UK/Canada public aid for video games).
48%: publisher and platform receivables (Steam payments, consoles, mobile stores).
13%: other receivables.
0%: financing dedicated solely to user acquisition in the observed portfolio.
For borrowers outside the United Kingdom, Triple Dragon may create a British SPV to standardise the applicable law.
My reading: Vitalijs Zalovs explained on Telegram that TD Bonds offer a guarantee at group level whereas loans carried by the dedicated vehicles are deliberately without parent company support: two complementary products, two risk profiles.
90-day buyback guarantee
If a loan is more than 90 days late, the lending company TD Funding 2025 Limited (United Kingdom) must buy it back from investors. It is not the Luxembourg platform Triple Dragon Funding SARL that bears this obligation.
The group claims a track record of covering investors in the event of past defaults, with no guarantee for future loans. No loss for investors has been observed to date.
Early Exit and liquidity
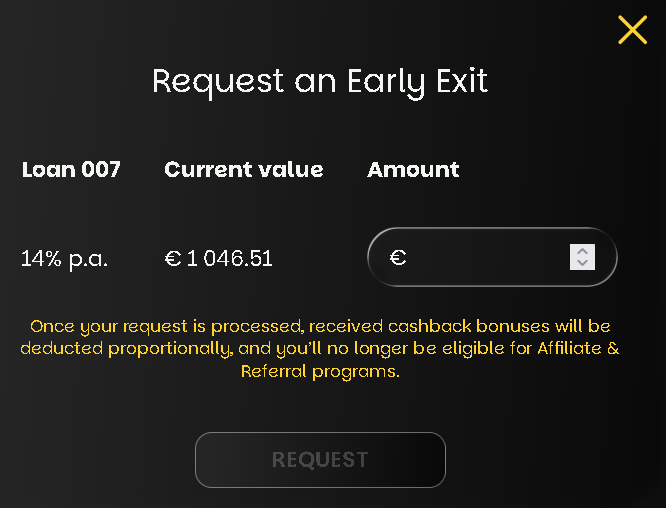
As on many P2P platforms at the beginning, the main weakness remains liquidity: your capital remains committed until the loan matures or until early repayment by the borrower.
TD Funding has offered Early Exit on the first eligible projects since July 2026: after a minimum holding period of 6 months, you can put your position up for sale. The feature has already been tested positively by some investors.
Small caveat: it is a kind of secondary market. A buyer has to take over your share, which is never guaranteed.
Risks to know

Risk of capital loss.
Video game sector: cancellations, release delays, dependence on a few commercial successes.
Collateral: payment delays (tax credits, royalties) and slower enforcement in the event of a publisher dispute.
Triple Dragon group: high financial leverage and need for transparency on financial statements.
Platform: no ECSP / MiFID II authorisation, licence applied for but not yet obtained.
Liquidity: Early Exit depends on a buyer on the secondary market.
To be reserved for a P2P diversification strategy, with an allocation that you can immobilise for the duration of the loans. The platform is still young: it needs to be given time.
Debitum vs TD Funding: understand the difference

Triple Dragon raised funds for a long time via Debitum (TDFD entity), a Latvian platform authorised under MiFID II.
Triple Dragon's rating on Debitum was downgraded in the past (around C → D-), which fuelled the debate around the migration to the proprietary platform. The group argues that the direct model allows for better investor conditions; sceptics point to a need for refinancing after tensions with the Debitum platform. Both interpretations coexist: factor this into your decision.
White Label Solutions and the Ventus Energy link
TD Funding's technical infrastructure is provided by White Label Solutions (SIA WIN INVESTMENTS), the same provider as Ventus Energy, Devon, Asterra Estate, etc. This common point fuels suspicions of proximity between these platforms.
The group's official position (Pieter van der Pijl, summer 2026): no shareholding link between Triple Dragon and Ventus Energy; WLS is a software provider; data is hosted in the cloud with a copy of the code on the platform side; TD Funding's legal structure is different (you do not lend directly to the Luxembourg SARL as on certain energy models).
Taxation in France
Interest received on TD Funding is income from movable capital. There is no Luxembourg withholding tax on these flows (unlike certain Bulgarian or Latvian platforms with withholding tax). See my article on P2P withholding tax.
For an individual tax resident in France:
Flat tax (PFU): 31.4% since 2026 (12.8% income tax + 18.6% social contributions), or
Progressive scale + social contributions (global option).
Form 3916: foreign account to be declared every year.
Form 2778-SD: used to declare and pay the levies on this interest. Below the reference taxable income thresholds, you can request an exemption from the 12.8% advance payment, but the filing obligation remains (practice varies depending on local individual tax offices (SIP)).
The bonuses from affiliation (affiliate rebates and platform campaigns) are in principle taxable as financial income: confirm with your adviser.
From your investor area, you can export your transactions and interest. A dedicated tax report page also allows you to generate a PDF for the chosen period (login required), which makes preparing your return easier.
My experience and position
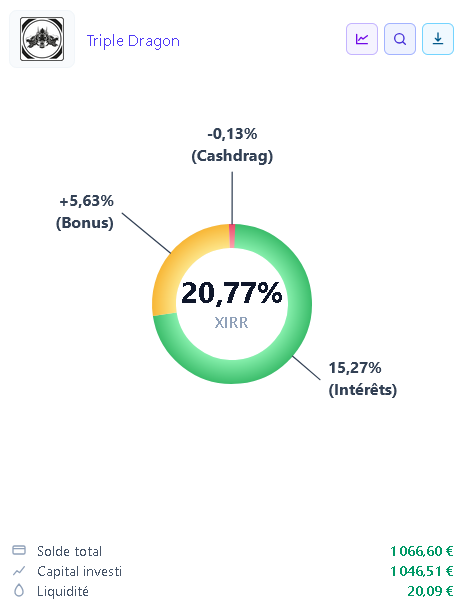
Since late January 2026, I have invested €1,000 via TD Funding, in loan 007.
Cumulative interest received: €94
Bonus / cashback: €30
Capital still invested: €1,000.
The chart above shows my XIRR (internal rate of return) observed over the period.
Advantages and disadvantages
✅ Advantages
Guarantees: collateral, priority over cash flows and 90-day buyback.
Group track record: profitable company with no losses.
Experienced team in gaming and P2P.
High return in a gaming niche rarely covered elsewhere.
Daily interest and possible compounding.
Geographic diversification.
Early Exit on eligible projects.
No withholding tax; legal entities accepted (sections Taxation and KYC).
Affiliate cashback 1% over 60 days.
⚠️ Disadvantages
€1,000 ticket.
No auto-invest.
No ECSP / MiFID II authorisation.
Interface in English, with no mobile app.
Recent platform (2026).
Limited transparency on the group's financial statements.
Bonus and registration
Via my affiliate link:
1% cashback on the total amount invested during the first 60 days following registration (uncapped on the amount communicated by the programme: e.g. €10,000 invested → €100 cashback).
Link: https://liberte-financiere.net/t.php?l=160
The platform also offers one-off campaigns (cashback on TD Bonds 1-2%, “Refer a Friend” referral). Check the terms in force in your investor area at the time of your deposit. All P2P codes: Bonus page.
Frequently asked questions about Triple Dragon Funding
Is TD Funding reliable?
The Triple Dragon group has nearly ten years of experience with no losses for investors and a portfolio with no short-term delays. “Reliable” does not mean risk-free: no European authorisation, recent platform, bond product likely riskier than secured loans.
Is TD Funding regulated?
Not in the sense of ECSP or MiFID II authorisations. The platform uses the prospectus exemption (149 investors per European Union country). Luxembourg licence application announced.
What is the minimum investment?
€1,000 per loan or per bond tranche (unless otherwise stated on the product sheet).
TD Bonds or secured loans: which should you choose?
Secured loans should be favoured if you are looking for identifiable studio collateral. TD Bonds may be suitable if you accept the credit risk linked to the group for a similar rate, to which cashback may be added. This is a structure closer to an unsecured corporate bond.
Is it the same as on Debitum?
No. Debitum is a MiFID II-authorised platform in Latvia. TD Funding is the group's direct platform, with other dedicated vehicles and other contractual documents.
Is TD Funding linked to Ventus Energy?
Same technical provider (WLS), no announced shareholding link. Reputational risk only.
Can I exit before maturity?
Early exit is possible after a minimum period on eligible projects. Generally 6 months.
How do you declare TD Funding income in France?
Interest is income from movable capital. Plan for form 3916 and possibly a monthly declaration (see section above). No withholding tax in Luxembourg. See the dedicated P2P withholding tax page.
Is there auto-invest?
No: manual selection is mandatory for each project.
Invest via a company?
Yes, legal entity accounts are accepted (enhanced KYC).
Is 14% realistic?
That was the rate displayed on loans before August 2026; new loans are at 13.5%. TD Bonds remain at 14% + cashback. Gross, before French taxes. Be careful, there is always a risk.
Are the loans guaranteed by Apple or Google?
No. The loans are backed by the borrowers' receivables (payments from distribution platforms, publishers, administrations). This is not a guarantee from major technology companies on your capital.
Conclusion
TD Funding is a gaming P2P platform with a strong track record from the parent company, attractive returns and solid guarantees. It also brings sectoral and geographic diversification that is rare in P2P.
But it should be noted that to date, it does not (yet) have European authorisation. In addition, the platform's youth and the need for financial transparency remain points to watch.
To open an account with 1% cashback (over 60 days): TD Funding registration via Liberté Financière.
And as always, don't give up on ANYTHING!
Last editorial update: September 2026