Twino, a MiFID II regulated platform, is one of the very first European peer-to-peer lending platforms, launched in Riga in 2015, back when Mintos was only just getting started. I started investing there in September 2026, first in the liquid FLEXI product, then by placing 5 000 € in 12-month notes in October.
In this review, I cover Twino's history and management, how the notes work, Fincard and its financial statements, regulation, the Polish proceedings, the statistics, the platform's track record, FLEXI, the secondary market, taxation and the comparison with other platforms. I will update it regularly with my results.
This article is not sponsored by Twino. Some links are affiliate links: Twino has no permanent welcome bonus, but if you sign up with my link, you benefit from the cashback campaigns it regularly runs for new investors, and you support my work at no extra cost.
- Up to 2% cashback on your investments during your first 90 days
During the campaign, this offer replaces the usual offer.
Get the offer →Until 22 November 2026
Twino at a glance
Criterion | Twino |
|---|---|
Founded | Group founded in 2009 by Armands Broks, investment platform launched in 2015 |
Headquarters | 🇱🇻 Riga (Latvia) |
Company | AS TWINO Investments (no. 44103143823) |
Regulation | MiFID II investment firm supervised by the Bank of Latvia, MiCA authorisation since June 2026 |
Lender | Netcredit (Fincard Sp. z o.o., Poland), about 96 % of outstanding loans |
Products | 3, 6 or 12-month notes (8.5 to 12 %) and FLEXI (6 %, withdrawal at any time) |
Volume | €1.17 bn invested since 2015, €40 m outstanding in September 2026 |
Investors | About 21 000 registered |
Secondary market | Yes, free of charge |
Minimum investment | 1 € per note, 10 € for FLEXI |
Fees | None to invest; inactivity fees on dormant accounts |
Withholding tax | 5 % (Latvia), recoverable in France |
Bonus | Regular cashback campaigns, see my Twino bonus code page |
Twino is one of the few P2P platforms to hold an investment firm licence, the same level of authorisation as Mintos. You can compare its regulatory framework with that of other platforms in my P2P comparison (regulation view).
From 2009 to 2026: the history of Twino
The group was born in 2009 in Riga, founded by Latvian entrepreneur Armands Broks: it started as an online consumer credit company, active in Latvia, Poland, Russia, Kazakhstan and Georgia. In 2015, the group launched its investment platform to fund its loans with money from retail investors. The model was then the same as on every Baltic platform: the investor buys shares of loans, with a buyback guarantee in case of delay. In October 2019, the group passed one billion euros in loans issued.
Two turning points then shaped today's Twino. The first is regulatory: on 31 August 2021, AS TWINO Investments obtained an investment firm licence, and in July 2022, investments took the form of financial securities issued with a prospectus. The second is a refocus: after the war in Ukraine, which blocked Russian repayments, and the end of its activities in Asia, the platform concentrated on Poland.
Since 2025, Twino has been in full revival: a new CEO, a new mobile app, the launch of FLEXI in April 2026, MiCA authorisation in June and full recovery of the Russian receivables in August.
Date | Event |
|---|---|
2009 | Group founded by Armands Broks |
2015 | Launch of the investment platform |
October 2019 | The group passes €1 bn in loans issued |
31 August 2021 | Investment firm licence (AS TWINO Investments) |
February-March 2022 | End of the Russian business |
July 2022 | Switch to notes backed by Fincard loans (Poland) |
March 2024 | End of activities in Vietnam and the Philippines |
22 November 2024 | Fincard licensed as a payment institution in Poland |
May 2025 | Nauris Bloks confirmed as CEO |
14 January 2026 | Philippines repaid in full, interest included |
27 April 2026 | Launch of FLEXI |
May 2026 | New iOS and Android mobile app |
4 June 2026 | MiCA authorisation (crypto-assets) |
5 August 2026 | Full recovery of the Russian receivables |
The founder and the management team
 Armands Broks (LinkedIn) founded the group and ran it from 2009 to 2019. He is the sole shareholder of AS TWINO Investments and chairs its supervisory board. He also controls FINNO Holding, Fincard's parent company. The platform, the issuer of the notes and the lender therefore belong to the same group: his interest in making Twino work is total, but there is no independence between the party selling the notes and the party borrowing the money.
 Nauris Bloks (LinkedIn) has led Twino since spring 2025, confirmed on 30 May 2025 after approval by the Bank of Latvia. He has known the company for a long time: a former head of IT for the group, then a member of the supervisory board from 2021 to 2023, he was working at DelfinGroup, another Latvian consumer credit player, before coming back. He was named "Fintech Leader of the Year" at the Baltic FinTech Awards 2026. Since he arrived, communication has become much clearer: a monthly CEO letter, published statistics and detailed explanations on every issue.
Before him, managers came and went at a fast pace:
Period | Manager |
|---|---|
2009 - 2019 | Armands Broks (founder) |
2019 - 2022 | Anastasija Oļeiņika (group); Roberts Lasovskis (AS TWINO Investments, 2021-2022) |
May - December 2022 | Anastasija Oļeiņika, then Karīna Caunīte-Orupe |
December 2022 - May 2025 | Helvijs Henšelis |
Since May 2025 | Nauris Bloks |
The management board also includes Artūrs Cekuliņš (LinkedIn) (legal and anti-money laundering) and Māris Čevers (LinkedIn) (chief risk officer). The supervisory board includes Mārtiņš Mellēns (LinkedIn) and Helvijs Henšelis (LinkedIn). The platform employs about 25 people.
How does Twino work?
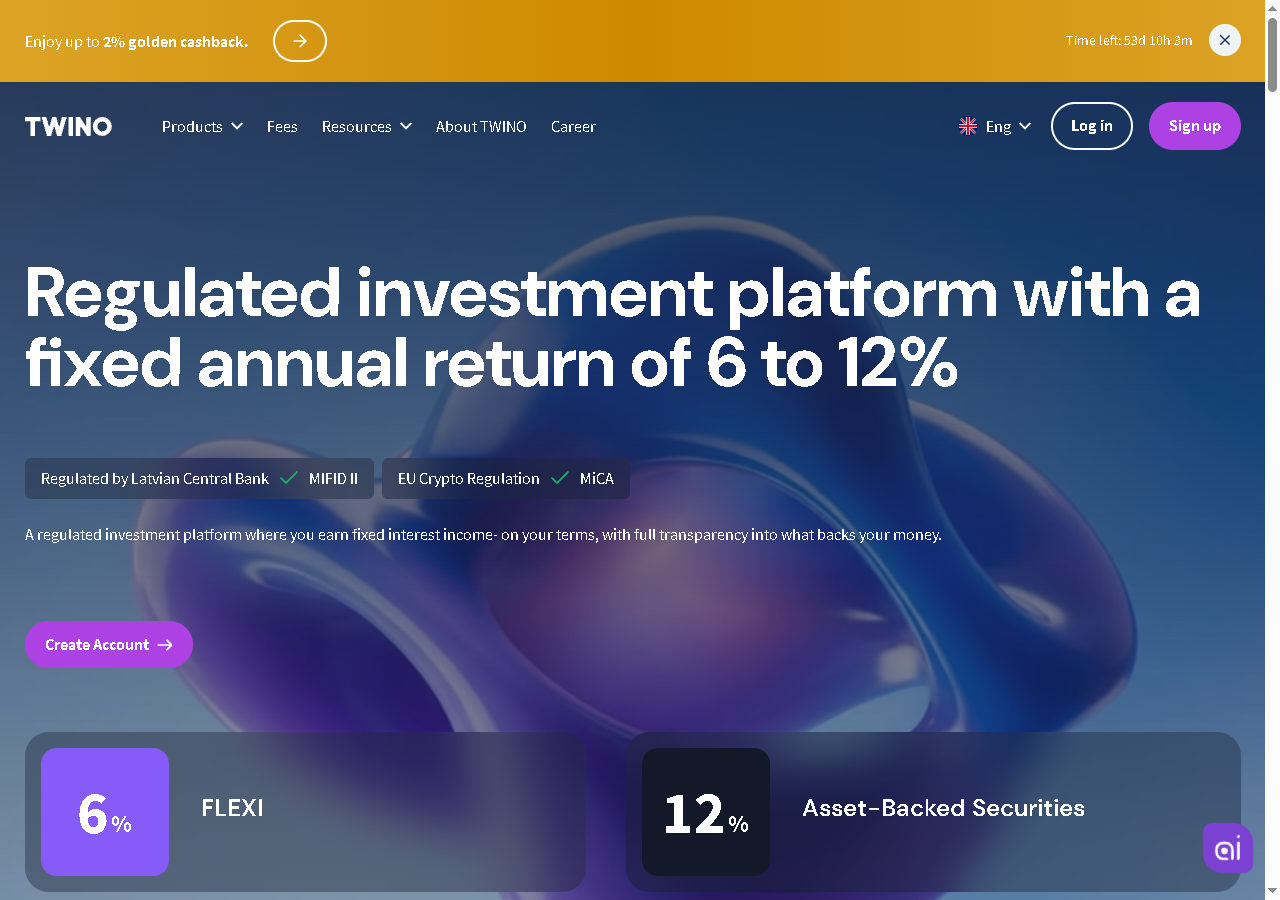
Your money funds consumer loans in Poland, but the structure is more tightly regulated than on most P2P platforms:
Netcredit (the company Fincard) grants revolving credit cards, up to 20 000 zlotys, to Polish individuals.
SIA TWINO Investments Poland, a group company registered in Latvia, lends Fincard the money it needs, at 10-13 % per year.
This company issues asset-backed securities backed by that loan, with a base prospectus approved by the Bank of Latvia.
You buy these notes on the platform, for 3 to 12 months. You receive interest every month and your capital at maturity.
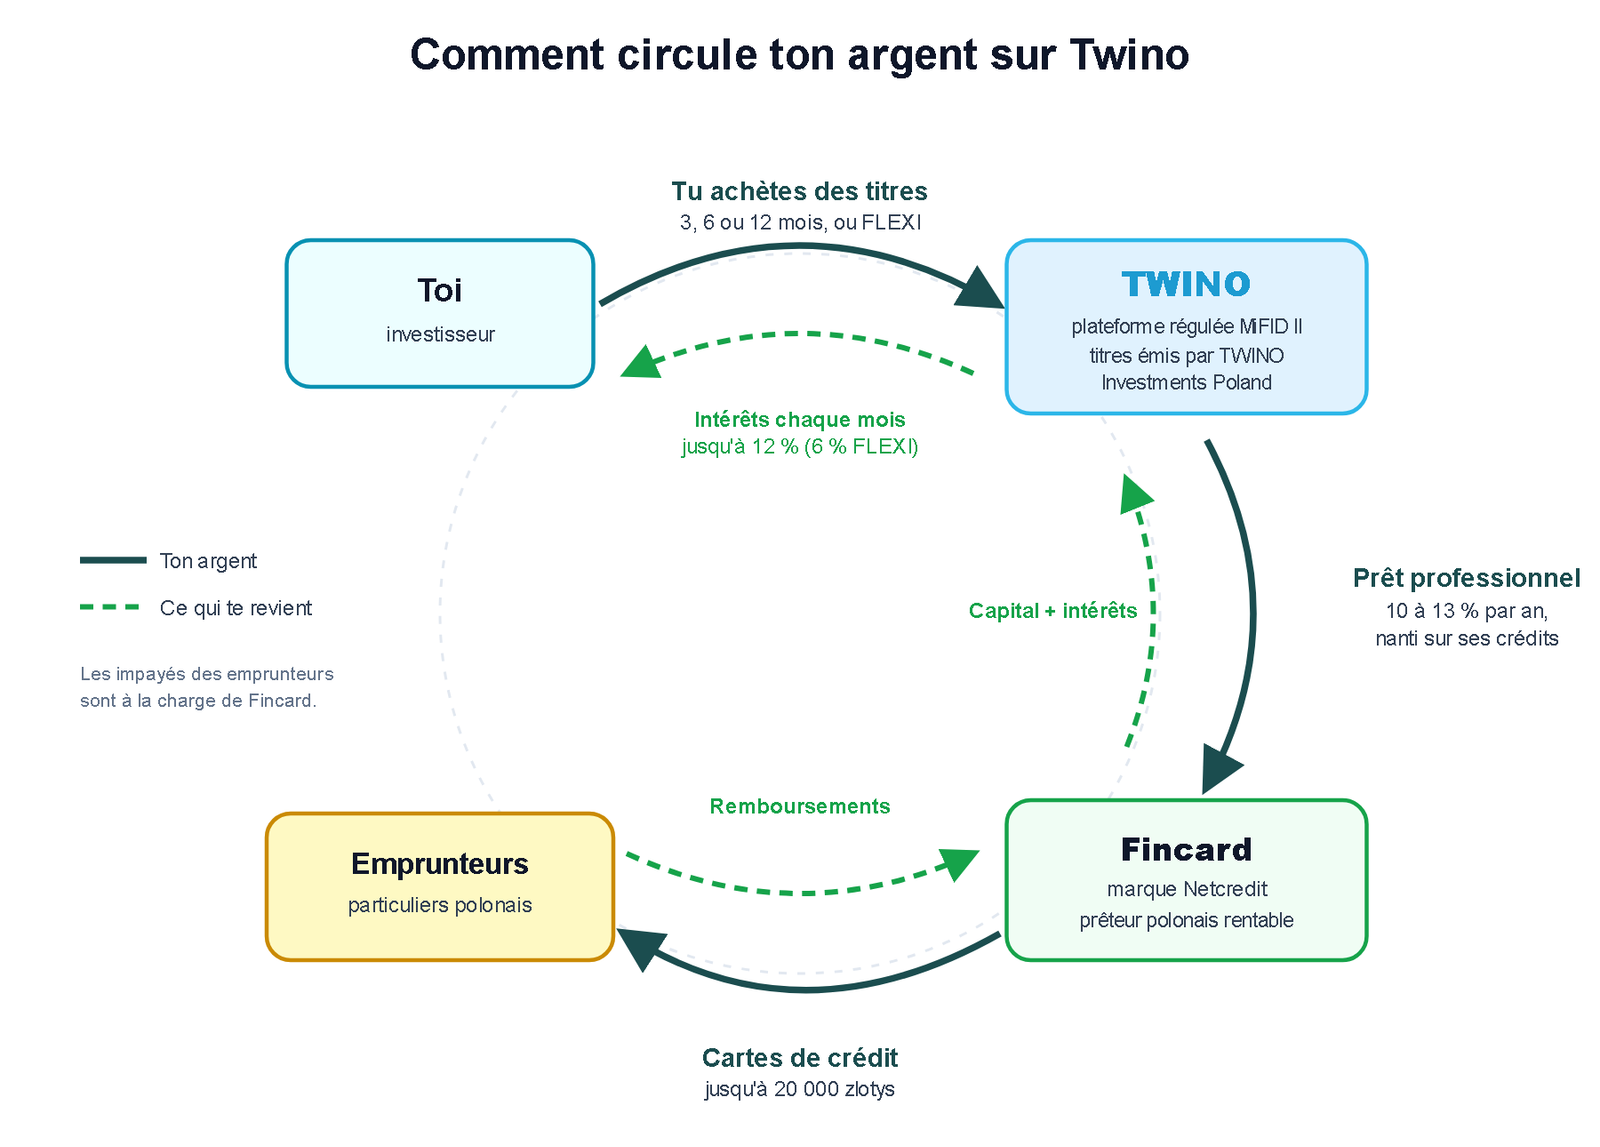
Your money is held in an account separate from Twino's own, as MiFID II requires, and the notes are registered in your name. If the platform went bankrupt, your notes would not fall into its bankruptcy estate.
No buyback guarantee: you lend to Fincard, not to the borrowers
On a platform like Mintos or PeerBerry, you buy a share of a specific borrower's loan, and the buyback guarantee requires the lender to buy that share back from you if the borrower stops paying. On Twino, you do not buy loans to individuals:
the issuer grants a business loan to Fincard;
this loan is secured by a pledge over Fincard's loan portfolio, meaning its customers' credit cards;
your notes are backed by this loan: your actual debtor is Fincard.
If a Polish customer does not repay their card, Fincard takes the loss, not you: you receive your interest as long as Fincard repays the issuer. A buyback guarantee would make no sense, since it would come from the company that already owes you the money. It is the same logic as Stikcredit on Afranga, where you lend to the credit company itself. Your risk is therefore concentrated on Fincard's financial strength, which I detail right below.
Netcredit (Fincard): Twino's lender
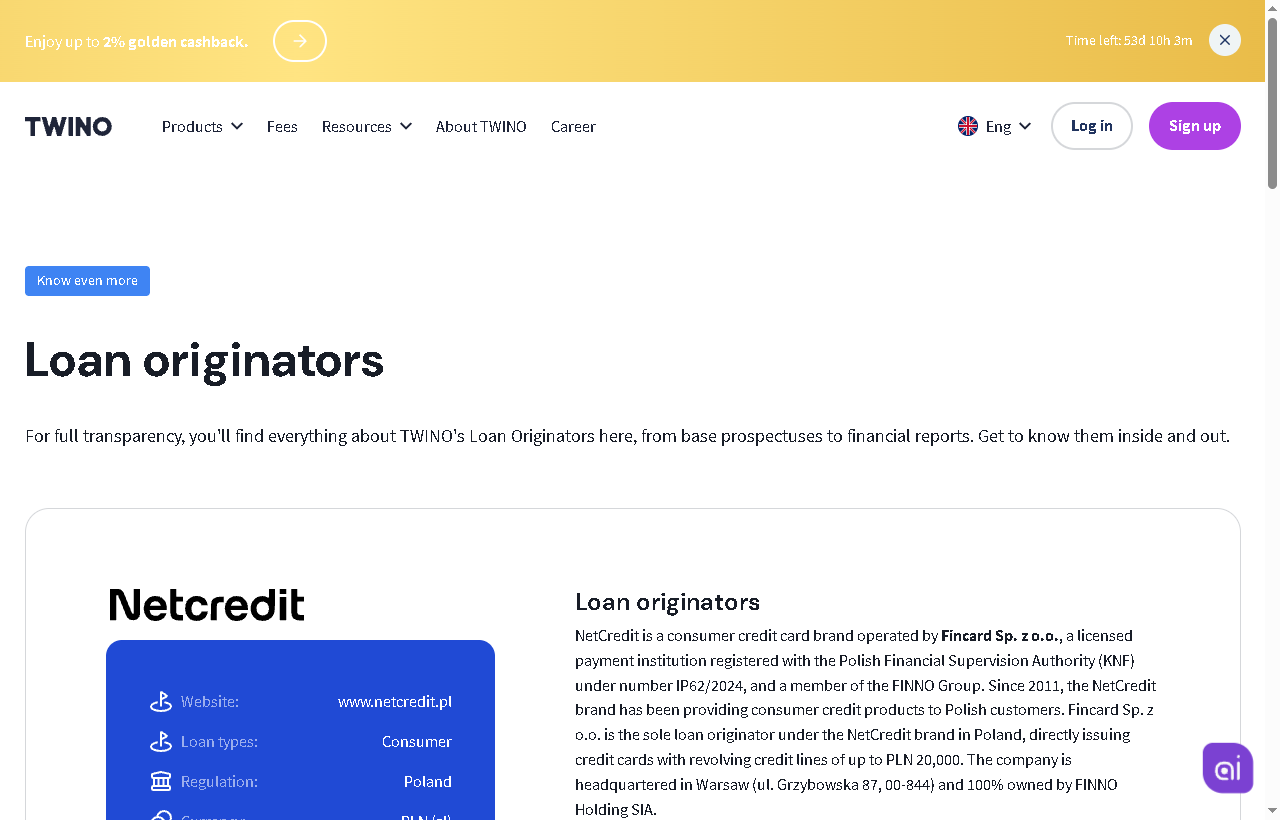
Fincard Sp. z o.o. is based in Warsaw. It operates the Netcredit brand, present in Poland since 2011, and the Halvo brand. Since 22 November 2024, it has been a payment institution licensed by the Polish financial authority (KNF, licence IP62/2024). It is 100 % owned by FINNO Holding (Riga).
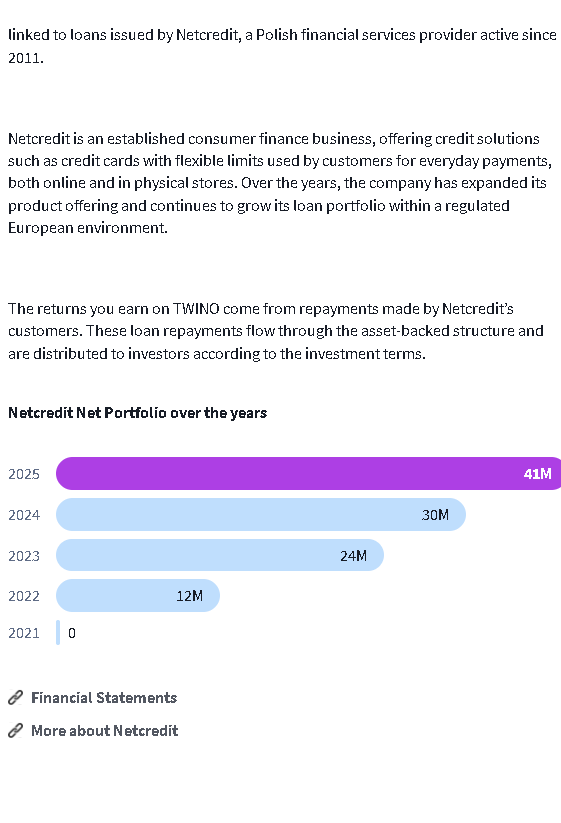
In 2024, Poland significantly tightened the rules on online consumer lending. The group therefore switched its business to revolving credit cards, a product regulated differently. On 1 September 2026, Netcredit accounted for 96 % of Twino's outstanding portfolio (standard notes and FLEXI), the rest corresponding to the former Vietnamese lender. Its portfolio funded through Twino has more than tripled since 2022:
Fincard's financial statements (2023-2025)
I analysed Fincard's audited annual accounts (amounts converted into euros at the year-end rate):
Fincard | 2023 | 2024 | 2025 |
|---|---|---|---|
Revenue | €33.7 m | €45.0 m | €54.1 m |
Net profit | €7.3 m | €7.9 m | €10.4 m |
Net margin | 21.8 % | 17.6 % | 19.2 % |
Equity | €7.9 m (27 % of the balance sheet) | €16.8 m (36 %) | €27.4 m (42 %) |
Audit opinion | Unqualified | Qualified | Qualified |
Fincard is highly profitable: about €10 m in profit in 2025, up 29 %, and equity more than tripled in two years. Its loans are highly diversified, with no card weighing more than 0.1 % of the portfolio, and its operating cash flows are positive.
Three points are worth monitoring:
the auditor's qualification in 2024 and 2025: Fincard has not booked any provision for the Polish proceedings;
the funding from the group: Fincard borrows most of its money from the issuer of the Twino notes (€31.5 m at the end of 2025);
the loans to the group: Fincard has lent €17.7 m to group companies, including €11.3 m to its parent company.
The details of each financial year are on my P2P financial statements (Fincard) page.
The UOKiK proceedings in Poland
UOKiK is the Polish consumer protection authority. On 15 June 2026, it made public its allegations against two credit card issuers, Easy Payment and Fincard. These are administrative proceedings, not a trial, and no decision has been issued to date.
What Fincard is accused of
In Poland, the interest rate on consumer credit is capped (18.5 % per year in 2024), and non-interest costs have their own cap. Between May and December 2024, Fincard charged, on top of interest, a fee for using the credit line, calculated on the amount used. According to UOKiK, these fees worked like interest and made it possible to exceed the legal cap. Fincard replies that the law allows interest and fees side by side, each within its own limit, and that it complied with both.
The timeline
Date | Step |
|---|---|
May to December 2024 | Period of the practice in question |
January 2025 | New fee model: 1.64 % of the granted limit per period, whether it is used or not |
16 May 2025 | Proceedings opened |
15 June 2026 | Allegations made public |
October 2026 | No decision |
Next | UOKiK decision, then possible appeal before the Warsaw court |
My analysis: a limited and absorbable risk
A limited period: the proceedings cover eight months of 2024. Since January 2025, Fincard has applied a different fee model, calculated on the granted limit and no longer on the amount used, which does not fit UOKiK's argument.
A bearable fine: it is capped at 10 % of revenue, i.e. about €5.4 m at most. That is roughly six months of Fincard's profit and less than 20 % of its equity.
Refunds to customers are the only unknown: if the 2024 practice were ruled illegal, customers could claim back the fees paid over that period.
Time works in the investor's favour: the proceedings have been running since 2025 and a decision would be followed by an appeal. The notes last 12 months at most, which leaves time to react if the situation changed.
I am keeping an eye on the future Polish consumer credit law, which will transpose the new European directive by 2027. That law will set the market rules for the long term.
Source: UOKiK press release, Fincard's annual accounts and the Polish press.
Regulation and safety
AS TWINO Investments is an investment firm licensed and supervised by the Bank of Latvia under the European MiFID II framework (licence no. 06.06.08.720/536). It has also held a MiCA authorisation since June 2026 and a European passport to offer its services in 11 countries, including France.
Segregation of assets: your money and your notes are kept separate from Twino's accounts.
Investor compensation: if Twino went bankrupt without being able to return your assets, the Latvian compensation scheme would step in, up to 20 000 €.
Transparency: base prospectus, key information document and final terms for each issue, accounts of the issuer and the lender published.
Controls: minimum capital, annual audit, Bank of Latvia inspections.
This protection covers the platform, not the credit risk: if Fincard stopped repaying, compensation would not apply. To go further, read my article P2P crowdlending regulation: MiFID II, ECSP and risks.
Twino's statistics
Indicator | Value |
|---|---|
Cumulative investments since 2015 | €1.17 bn |
Interest paid to investors | Over €30 m (343 530 € in August 2026 alone) |
Registered investors | 20 828 |
Outstanding portfolio | €40.1 m |
Average rate | 11.93 % |
Loans in recovery | 4 % of the outstanding portfolio, only the former Vietnamese lender |
FLEXI | Over €2 m issued, more than 2 100 investors |
Twino is a modest-sized platform, not comparable with Mintos, but stable. Apart from the Vietnamese case, current loans show no incidents.
Source: Twino's official statistics as of 1 September 2026.
The platform's accounts
AS TWINO Investments, the company that operates the platform, is separate from Fincard. Its accounts are audited by BDO:
AS TWINO Investments | Fees | Net profit | Equity |
|---|---|---|---|
2021 | 367 127 € | - 172 136 € | €1.78 m |
2022 | 1 783 203 € | + 178 488 € | €1.95 m |
2023 | 2 300 556 € | - 2 702 € | €1.95 m |
2024 | 2 991 540 € | + 362 385 € | €2.31 m |
2025 | 2 560 234 € | + 92 309 € | €2.41 m |
The platform is well capitalised: no financial debt, €1.49 m in cash, a regulatory solvency ratio of 206 % and an unqualified audit opinion for 2025. Its profitability fell in 2025, with fees down 14 % and higher marketing spending. This does not directly affect your money, which does not appear in its accounts. The analyses of the 2024 and 2025 financial years are on my P2P financial statements (Twino) page.
The products: fixed-term notes and FLEXI
Fixed-term notes | FLEXI | |
|---|---|---|
Fixed rate | 8.5 % (3 months), 10 % (6 months), 12 % (12 months) | 6 % |
Interest | Paid every month | Calculated daily, paid every month |
Term | 3 to 12 months | None |
Early exit | Secondary market | Withdrawal at any time |
Minimum | 1 € per note | 10 € |
Maximum | None | 10 000 € per investor |
Cashback campaigns | Yes | Usually not |
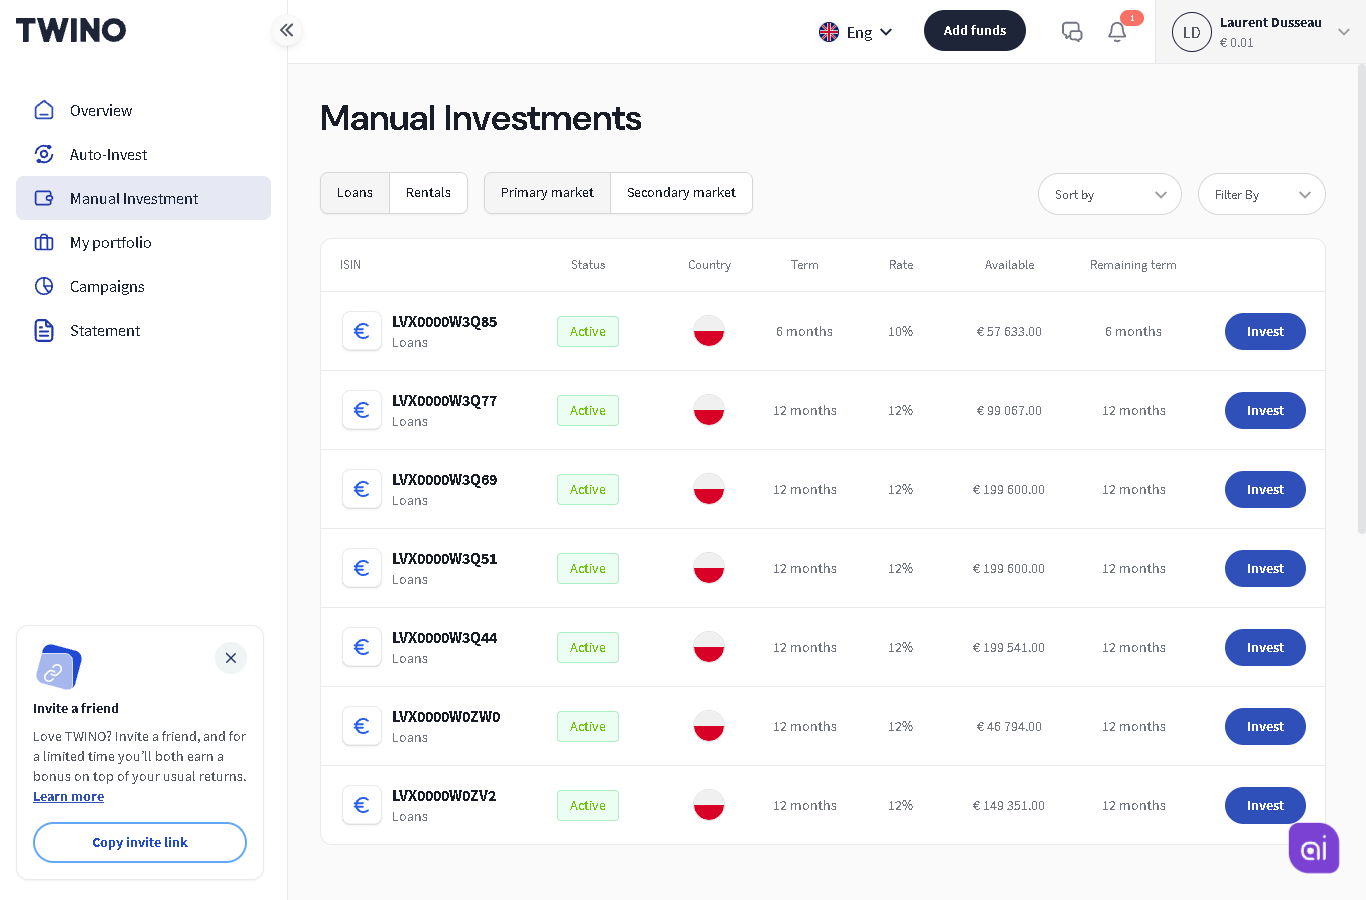
The primary market only offers Polish notes, at 6 months (10 %) or 12 months (12 %) at the time of writing:
FLEXI
Launched in April 2026, FLEXI is the equivalent of Bondora Go & Grow or Monefit SmartSaver: your money is placed in 12-month Netcredit notes, but you can withdraw it whenever you want, with no fees or discount, instantly to your Twino wallet and then in about two business days to your bank. Liquidity rests on three layers:
new deposits and repayments;
a cash guarantee deposited by Netcredit, equal to 10 % of the notes issued;
as a last resort, early repayment of the notes by Netcredit.
As long as withdrawal requests stay below 10 %, Twino buys back within 5 business days. Beyond that, withdrawals may be spread out over time. FLEXI is therefore very liquid in normal times, but it is not a savings account. Since August 2026, you can also have the repayments of your notes transferred automatically to FLEXI.
The secondary market
To exit a note before maturity, you sell it on the secondary market, free of charge, at a premium of up to 4.9 % or a discount of up to 29.9 %. It is a real advantage, and one of the reasons I decided to invest. Selling does, however, depend on there being buyers.
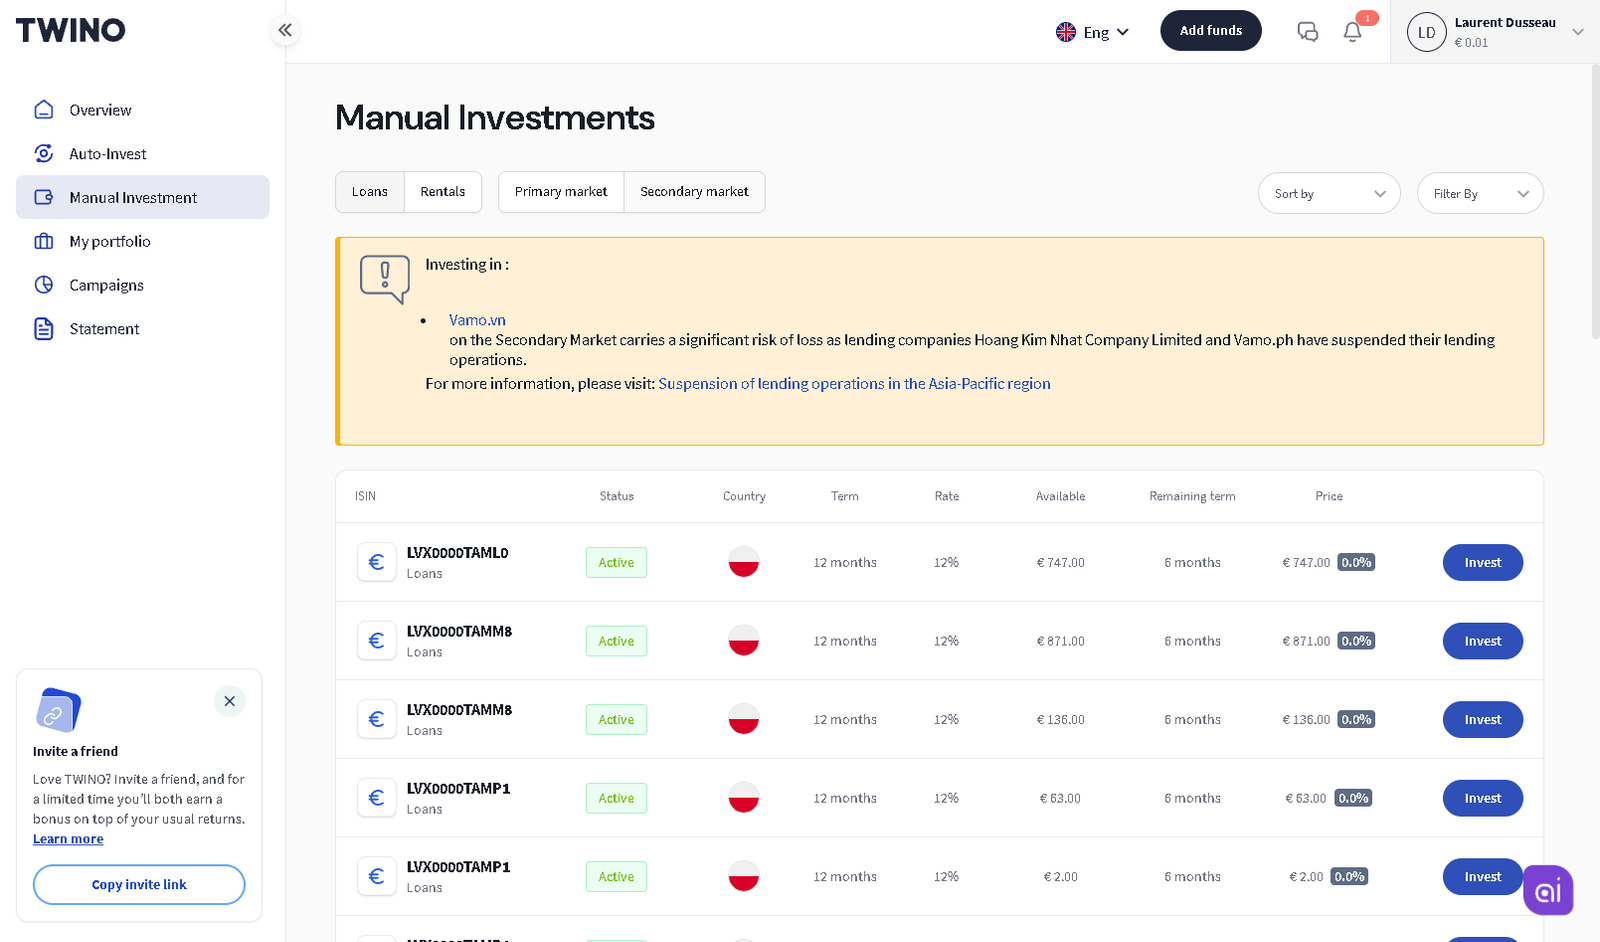
Twino displays a warning on the old Vietnamese notes still offered for resale: they are the only ones to avoid.
Auto-invest
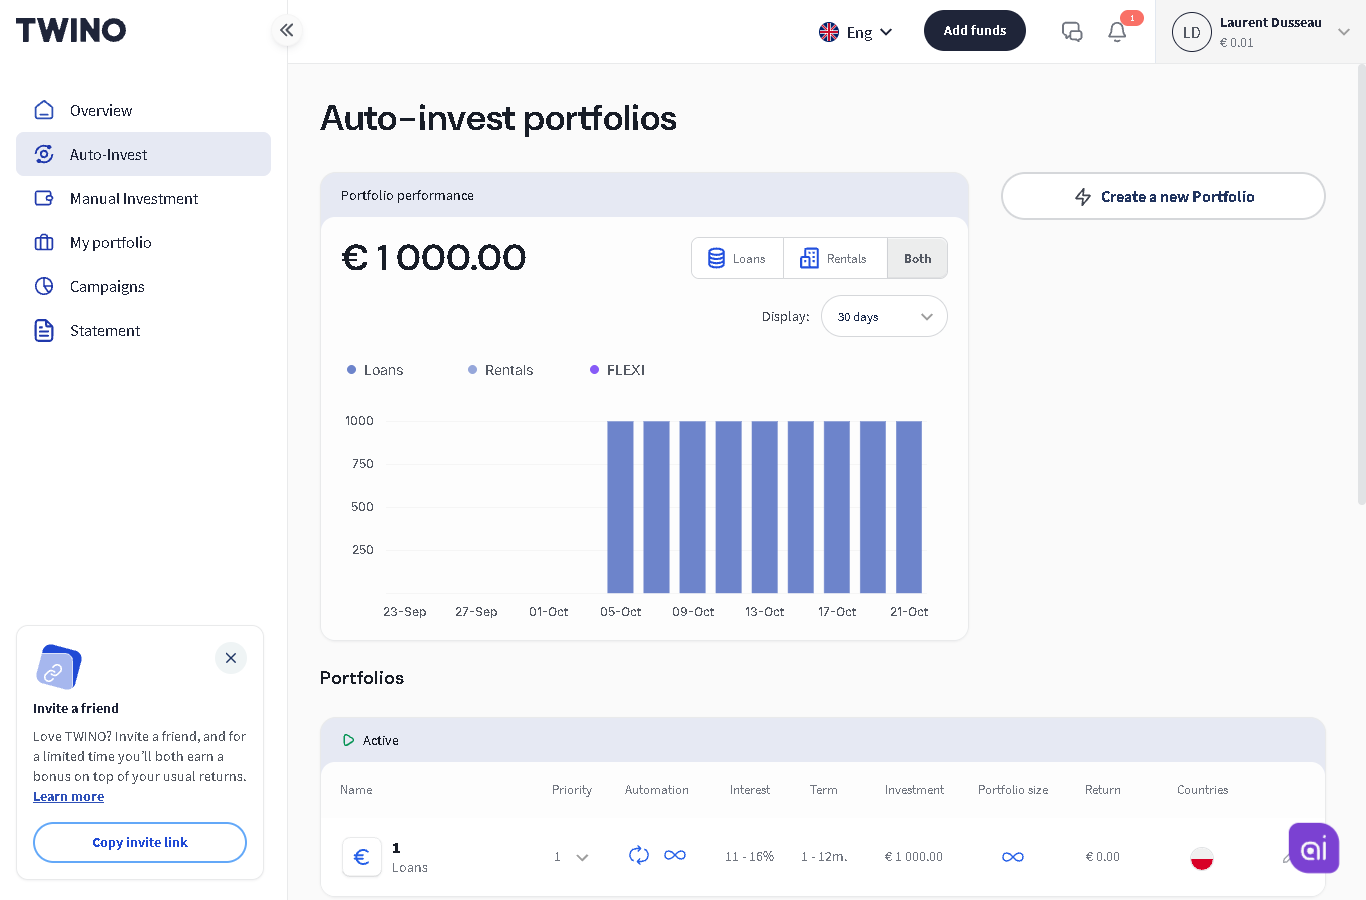
Auto-invest automatically reinvests your money according to your criteria. With a single lender, the settings come down to the amount and the term: 12 months for the best rate.
How to invest on Twino, step by step
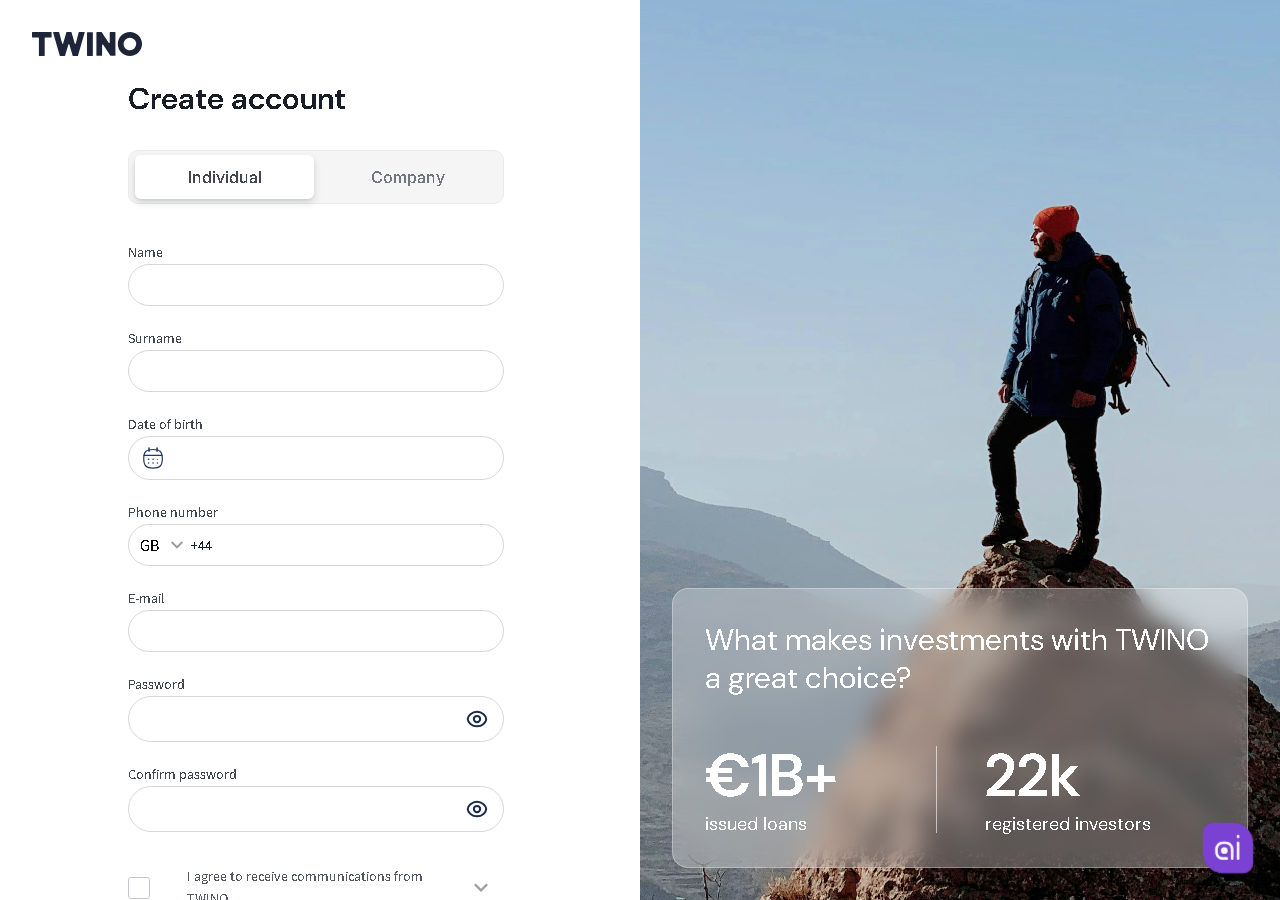
Open the website with my link and create your account. The site is available in English, German, Latvian and Spanish.
Verify your identity: ID document, selfie and a short suitability questionnaire required by MiFID II.
Activate the current cashback campaign, if there is one, in your profile under "Campaigns". Without this step, no cashback.
Make a bank transfer from a bank account in your name, free of charge.
Invest on the primary market, preferably in 12-month notes, or set up Auto-invest.
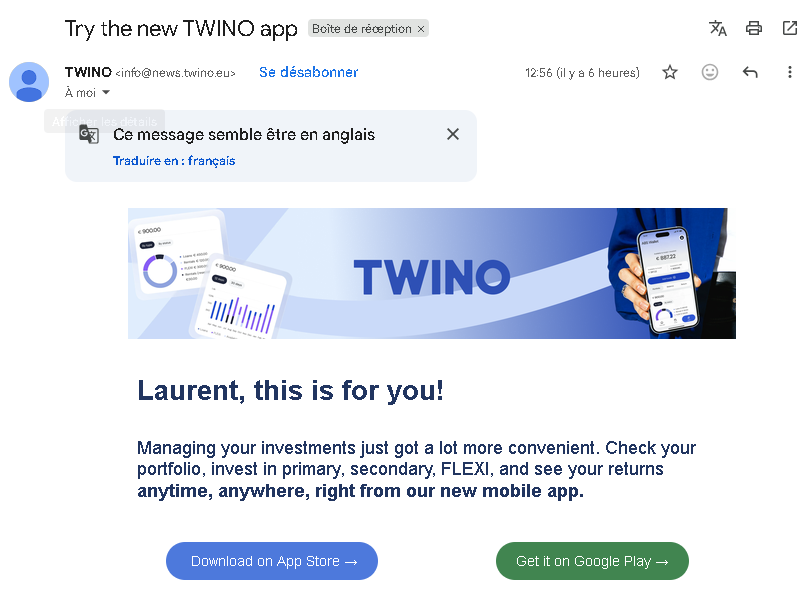
The Twino mobile app (iOS and Android) lets you manage everything from your phone:
Fees
Registration, deposits, investments and withdrawals to an EU account: free.
Secondary market: free.
Inactivity fee: up to 10 € per month if you stop investing for six months while leaving uninvested money in your account. If you stop investing, withdraw your available cash.
Withdrawals outside the EU / EEA: 35 €.
The platform's track record: Russia, the Philippines, Vietnam
A platform active for more than ten years has inevitably been through crises. Here is how Twino handled its own:
Case | What happened | Outcome |
|---|---|---|
Russia (Moneza) | Repayments blocked from 2022 by capital controls: €6.9 m affected | Full recovery announced on 5 August 2026, after capped monthly repayments and an early buyback offer at a discount, at each investor's choice |
Philippines (Vamo) | Business stopped in 2024, 855 000 € outstanding | Repaid in full, interest included (January 2026) |
Vietnam (Vamo) | Stopped in March 2024, lender insolvent | €1.6 m in recovery, Twino registered as a creditor in the liquidation |
Real estate (Rentals) | Product launched in 2023, disappointing results | Gradually wound down since 2025, properties being sold |
Investors exposed to Russia and the Philippines got their money back, which is far from a given in P2P. Vietnam remains the only open case. These activities belong to the past: today, every new investment goes to Netcredit.
The risks you need to know
Risk of capital loss: there is no buyback guarantee. If Fincard could no longer repay its loan, you could lose part of your money; the 20 000 € compensation only covers the platform's bankruptcy.
Liquidity risk: your notes are locked until maturity. The secondary market and FLEXI work well in normal times, but in a crisis you would have to sell at a discount or wait.
Geopolitical and concentration risk: a single lender, in a single country, Poland. Your Twino portfolio depends on Netcredit's health and on Polish rules: the UOKiK proceedings and the future consumer credit law could weigh on its profitability.
Single group: the platform, the issuer of the notes and the lender belong to the same shareholder.
Taxation in France
Twino applies a 5 % withholding tax on interest (Latvia), which I can see on my statement. The France-Latvia tax treaty lets you offset it against your French tax. The details are in my article P2P withholding tax.
In France, interest is subject to the 31.4 % flat tax, or to the progressive scale if that works out better for you. Twino withholds nothing on the French side: you declare the interest (forms 2047 and 2042) and your foreign account (form 3916). Twino provides an annual tax statement. All the steps are in my guide How to declare your P2P income for tax.
Twino compared with other platforms
Twino offers two very different products, hence two comparisons. For the other platforms, I show my actual XIRR excluding bonuses, measured on my own accounts in October 2026.
12 % notes: Twino, Afranga, Nectaro and Lendermarket
Criterion |
|
|
|
|
|---|---|---|---|---|
Platform | Twino | Afranga | Nectaro | Lendermarket |
Return | 12 % fixed (12 months) | 14.27 % (my XIRR) | 12.66 % (my XIRR) | 12.37 % (my XIRR) |
Regulatory framework | MiFID II | ECSP | MiFID II | ECSP |
Type of contract | Financial instrument | Crowdlending loan | Financial instrument | Crowdlending loan |
Withholding tax | 5 % | 10 % | 5 % | 0 % |
Compensation if the platform goes bankrupt | Up to 20 000 € | No | Up to 20 000 € | No |
🎁 Bonus |
Twino sits in the middle in terms of return and stands out for its framework: along with Nectaro, it is the only one of these four platforms regulated under MiFID II. Afranga pays more, with a 10 % withholding tax that cannot be recovered in France.
FLEXI: Twino, Bondora Go & Grow, Monefit and Modena
Criterion |
|
|
|
|
|---|---|---|---|---|
Product | Twino FLEXI | Bondora Go & Grow | Monefit SmartSaver | Modena |
Return | 6 % fixed | 6.00 % (my XIRR) | 7.50 % (my XIRR) | 8.66 % (my XIRR) |
Regulatory framework | MiFID II | No investor licence | No investor licence | No investor licence |
Cap | 10 000 € | None | None | None |
🎁 Bonus | — |
FLEXI is the only one of these products to benefit from a MiFID II framework, but it is also the lowest-paying and the only one with a cap. That is why I chose the 12-month notes. My full review of Monefit is here, and all the criteria are in my P2P comparison.
My investment on Twino
I started in September 2026 by testing FLEXI with 5 000 €: interest came in every day and I got my money back instantly, with no fees. In October, I placed 5 000 € in 12-month Netcredit notes at 12 %. I have also signed up for the cashback campaign reserved for existing customers, which should earn me up to 2 % on these notes.
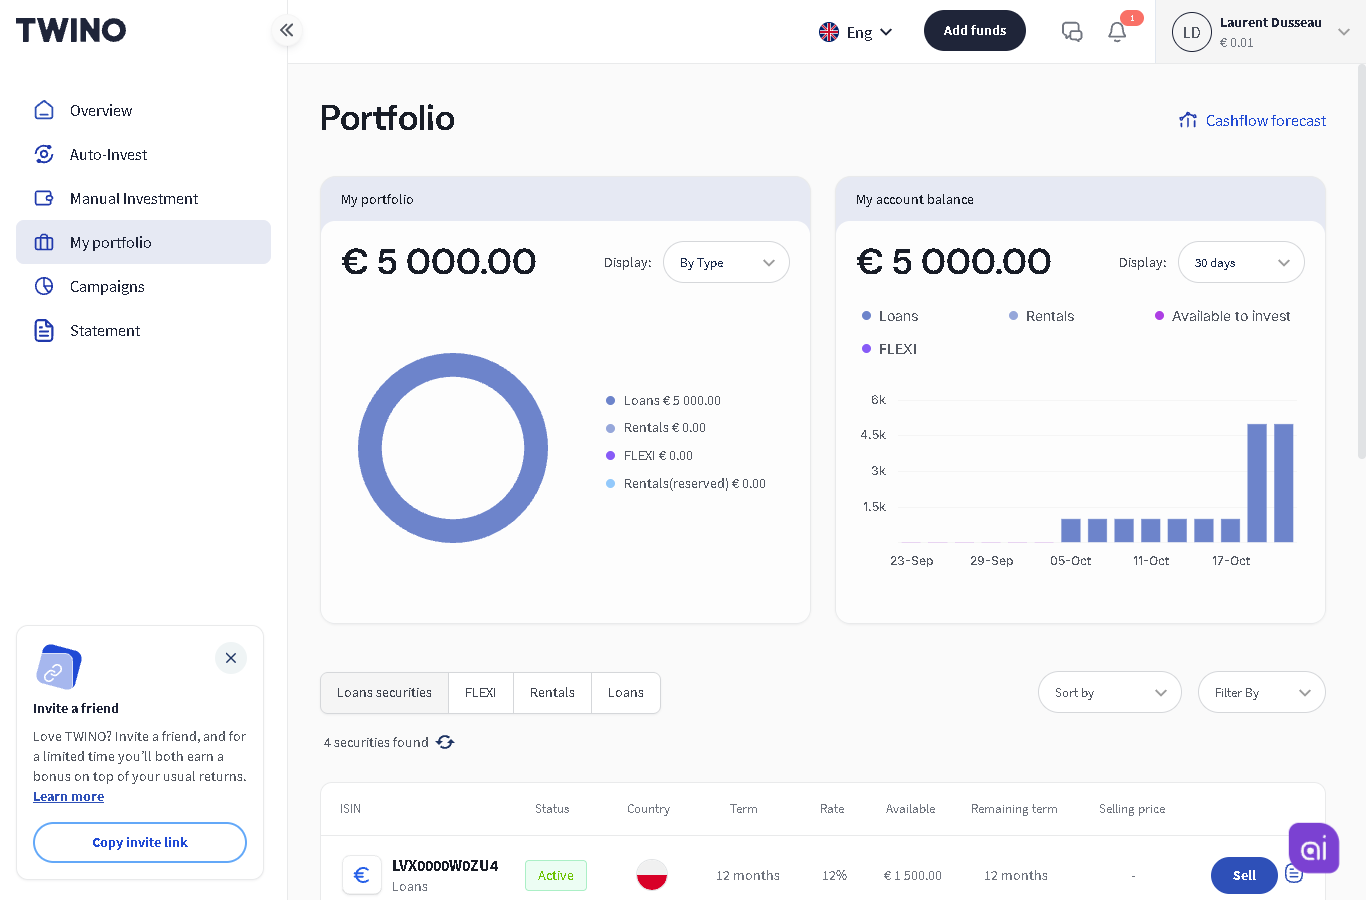
What convinced me: a MiFID II licence, a profitable lender with audited accounts, more than ten years of track record, past cases settled, a free secondary market and a fixed 12 % return. I will update this article with my interest and my XIRR over the months, and you can follow my positions on my My P2P portfolio page.
⚖️ Pros and cons
✅ Pros
🏛️ MiFID II regulation by the Bank of Latvia, with compensation of up to 20 000 € if the platform goes bankrupt.
📈 12 % fixed over 12 months, interest paid every month.
🏦 A profitable lender: about €10 m in profit in 2025 for Fincard, 42 % equity ratio.
🔄 Liquidity: free secondary market and FLEXI.
🕰️ More than ten years of track record, with the Russian and Philippine cases repaid.
🎁 Regular cashback campaigns, for new sign-ups as well as existing customers.
⚠️ Cons
🎯 A single lender, from the same group as the platform: no diversification possible on Twino.
🇵🇱 UOKiK proceedings under way over the 2024 practice.
💸 Inactivity fees if your account lies dormant.
🇬🇧 No French version of the website.
Who is Twino for?
Twino suits you if you already have a P2P portfolio and are looking for a 12 % position on a regulated platform, or an alternative to Go & Grow with a better legal framework thanks to FLEXI.
Twino suits you less if it is your first P2P platform or if you are looking for broad diversification. As with any single-lender platform, I limit Twino to a small share of my P2P portfolio.
Twino bonus code and cashback
There is no code to enter at Twino: just go through my link. Twino regularly runs cashback campaigns, calculated on the notes bought during the first few months. When a campaign is running, it is shown here:
- Up to 2% cashback on your investments during your first 90 days
During the campaign, this offer replaces the usual offer.
Get the offer →Until 22 November 2026
The cashback applies to notes bought on the primary market, and the longer the term of the notes, the higher it is.
You need to activate the campaign in your profile, under "Campaigns", after completing identity verification.
You need to keep your notes until the payout, without listing them for sale on the secondary market.
Campaigns reserved for new investors generally do not apply to a sign-up made with another investor's referral link. My link is a partner link.
Twino also runs campaigns for customers who are already registered, and once you have signed up, you can refer your friends and family in turn. The detailed conditions of the current offer are on my Twino bonus code page.
Twino FAQ: frequently asked questions
Is Twino reliable?
Yes. Twino has existed since 2015, it is regulated under MiFID II by the Bank of Latvia and its investors got their money back in the Russian and Philippine cases. Its lender, Fincard, is profitable and its accounts are audited. The main point to watch is the concentration on this single lender.
Is Twino regulated?
Yes. AS TWINO Investments is an investment firm licensed by the Bank of Latvia under MiFID II, with a MiCA authorisation since June 2026. Fincard is a payment institution licensed by the Polish financial authority.
What return can you expect?
The notes pay 8.5 % (3 months), 10 % (6 months) or 12 % (12 months), FLEXI 6 %. The platform's average rate is 11.93 %. After the French flat tax, expect about 8 % net on the 12-month notes.
What is the minimum amount?
1 € per note and 10 € for FLEXI. FLEXI is capped at 10 000 € per investor.
Is there a buyback guarantee?
No, and that makes sense: since 2022, you no longer fund individual borrowers but a loan granted to Fincard, secured by its loan portfolio. Customer defaults are borne by Fincard (see above).
Do the UOKiK proceedings put my money at risk?
They target Fincard, not your notes, and concern a 2024 practice. With about €10 m in annual profit and a fine capped at about €5.4 m, Fincard has the means to cope with it.
Can you get your money back before maturity?
Yes, by selling your notes on the secondary market, free of charge, or by using FLEXI, where withdrawals are instant. Uninvested money can be withdrawn at any time.
What happens if Twino goes bankrupt?
Your notes and your money are kept separate from Twino's accounts and the loans continue to be repaid by Fincard. If Twino could not return your assets, the Latvian compensation scheme would step in, up to 20 000 €.
FLEXI or 12-month notes?
FLEXI for money you may need quickly (6 %), 12-month notes for return (12 %). In general, only the notes qualify for campaign cashback.
How do you declare Twino for tax?
Declare the interest (forms 2047 and 2042), offset the 5 % Latvian withholding tax and declare your account on form 3916. My step-by-step guide is here.
Can you invest through a company?
Yes, Twino accepts legal entities, with a check of the articles of association and the beneficial owners.
Can you invest from France?
Yes. Twino accepts residents of the European Union and the EEA, with free deposits and withdrawals by bank transfer. The website is not available in French, but the interface is simple.
Which bonus code should you use?
There is no code to enter: go through my link and activate the current cashback campaign in your profile. The current offer is shown at the top of this article and on my Twino bonus code page.
Conclusion: my review of Twino
Twino is one of the best-regulated P2P platforms in Europe. It relies on a profitable lender with audited accounts, pays a fixed 12 % on its 12-month notes and has turned the page on its old cases. The Polish proceedings concern a practice that has ended and remain within Fincard's means.
Its main point to watch is the concentration on Netcredit, which I offset by keeping Twino as one position among others in my portfolio. I have placed 5 000 € there and I will keep you posted on my results. If you want to get started, go through my link: you will benefit from the current cashback campaign, if there is one.
Investing involves a risk of capital loss. This article reflects my personal experience and does not constitute investment advice.